Protecting More Than Principal

The Cost of a 0% Return
Inflation continues to dominate headlines lately, and may reinforce a client’s financial concerns in the current economy. It tends to attract the most attention when it's high or expected to move even higher. While many clients focus on market performance, inflation can quietly reduce purchasing power, even when an account value doesn’t decline.
Warren Buffett argued that inflation is a hidden tax that quietly reduces the value of your money. He said, "The arithmetic makes it plain that inflation is a far more devastating tax than anything that has been enacted by our legislatures Inflation is in the headlines and attracts attention when it's high or expected to move even higher. The inflation tax has a fantastic ability to simply consume capital."1
The same concept applies when a client earns a percentage return during a year of inflation. While the account value may stay the same, what that amount of money can buy may decline.
Why That Difference Matters
Many fixed index annuity sales conversations emphasize protecting clients from market losses. While that protection is important, it can be only part of the equation. Advisors may be looking beyond principal protection and considering strategies that can provide a floor, even when markets decline.
A Three-Strategy Approach
The Enhanced Choice Index Plus annuity allows producers to customize 100% of a client's premium using two crediting strategies tied to the S&P 500® Dynamic Intraday TCA Index and the Fixed Account.
- Trigger Rate Strategy
Credits the Trigger Rate when the index is flat or positive and 0% when the index is negative. - Trigger Rate Plus Strategy
Credits the Trigger Rate when the index is flat or positive and 2% when the index is negative. - Fixed Account
Credits a guaranteed interest rate.
Putting it Into Practice
Suppose an inflation-conscious client wants to earn at least 2.50% on their money while maintaining the opportunity for indexed growth.
By purchasing an Enhanced Choice
Index Plus 7 and allocating 55% to the Fixed Account, 44% to the Trigger Rate Strategy and 1% to the Trigger Rate Plus Strategy on the S&P 500 Dynamic Intraday TCA Index, the client can:
- Earn 6.84% if the index is flat or positive.2
- Earn 2.50% if the index declines.2
Clients have the opportunity for indexed growth while establishing a desired floor for the minimum interest they can earn.
Creating A Guaranteed Floor
If the Index is flat or up, you can use these blended allocations to create a floor of your client’s choosing.
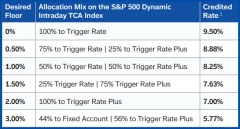
Hypothetical example for illustrative purposes only. Actual results will vary. Past performance is not indicative of future results.
Rather than focusing only on avoiding losses, this strategy creates a level of growth certainty that may help address inflation concerns. In addition to illustration projections, advisors can help clients choose a floor that aligns with their goals, risk tolerance and inflation concerns.
When inflation reduces purchasing power, having more certainty can make a difference.
Use Our Sales Concept Flyer to Help Create a Floor

More About Sales Insights & Tools


Related Products or Services

Doing business with The Standard is good for you and your clients. Our annuities offer innovative product design, desirable rates, competitive compensation, high industry ratings and excellent service.